Showing posts with label Bad Banks. Show all posts
Showing posts with label Bad Banks. Show all posts


28.10.09
Why Do Bankers Make So Much Money?
Below are some instructive comments from Rick Bookstaber, formerly a senior risk manager and derivatives creator for big banks in America.
Speaking from the point of view of a somewhat cynical insider who retains his essential faith in "free markets", Bookstaber comments: "I think the invocations of talent for money producers in finance are akin to those that, in times past, were set aside for the mystical powers of saints and witches."
Speaking from the point of view of a somewhat cynical insider who retains his essential faith in "free markets", Bookstaber comments: "I think the invocations of talent for money producers in finance are akin to those that, in times past, were set aside for the mystical powers of saints and witches."
Why Do Bankers Make So Much Money?
by Rick Bookstaber
23 October 2009
A tenet of economics is that in competitive markets there are no economic rents. That is, people get fairly paid for their efforts, their capital input, and for bearing risk. They are not paid any more than is necessary as an incentive for production. In trying to understand the reason for the huge pay scale within the finance industry, we can either try to justify the pay level as being a fair one in terms of the competitive market place, or ask in what ways the financial industry deviates from the competitive economic model in order to allow economic rents.
Do the banks operate in a competitive market?
No one expects competitive levels of compensation when there are deviations from a competitive market. In what ways might the banks – and here I mean the largest banks and those banks that morphed over the past year from being investment banks – fall away from the model of pure competition?
One way is through creating inefficiencies to keep competitive forces at bay. Banks can do this, for example, by constructing informational asymmetries between themselves and their clients. This gets into those pages of small print that you see in various investment and loan contracts. What we might call gotcha clauses and what the banks call revenue enhancers. And it also gets into the use of complex derivatives and other “innovative products” that are hard for the clients to understand, much less price.
Another way is to misprice risk and push it into other parts of the economy. The fair economic payoff increases with the amount of risk taken. If a bank takes on more risk it should get a higher expected payoff. If the bank can get paid as if it is taking on risk while actually pushing the risk onto someone else, then it will start to pull in economic rents. The use of innovative products comes up again in this context. They provide a vehicle for the banks to push risk to others at a less than fair price. Or, they can push the risk onto the taxpayers by hiding the risk and then invoking the too-big-to-fail protections when it comes to be realized. The current “heads I win, tails you lose” debate centers precisely on this point.
A third, and most obvious reason banks might not be economically competitive entities is the organization of the industry. There are barriers to entry. No one can just decide to set up a major bank. And there are constraint in the amount of business any one bank can do. As we have seen with Citigroup, there finally are diseconomies of scale – after a point the communication and management issues make the bank less efficient and more prone to crisis. If there is fixed supply, then the banks can push up the price of their services. The crisis over this past year has made matters worse. If you are one of those still standing, you are a beneficiary of that crisis, which has choked off the supply even further.
Are the workers getting paid fairly for their efforts?
An alternative to the idea that the industry is not competitive is that the industry really is competitive and those who are getting these outsized paychecks are being fairly compensated for their efforts. This comes back to the term we hear bandied about in conversations on banker compensation: talent.
There is no denying there are many smart people in the banking industry. (Though I think from a social welfare standpoint, we might have done better if some of those physicist and mathematicians that populate the ranks of the banks had found greener pastures in, say, the biological sciences). But I don’t buy the notion that there are so many who have the level of talent that justifies tens and even hundreds of million in compensation. I think this level of compensation, and the notion of talent behind it, is the result of the inherent uncertainty in the financial enterprise, one that makes it very difficult to assess talent. Indeed, I think the invocations of talent for money producers in finance are akin to those that, in times past, were set aside for the mystical powers of saints and witches.
Far more than other fields of endeavor, it is difficult in finance to tell if someone is good or lucky. A top trader or hedge fund manager might have a Sharpe Ratio of 1.0 or 2.0.But that Sharpe Ratio is nothing less that a statement that if you get a hundred people trading, a few will do well just by luck. (And it doesn’t matter if that Sharpe Ratio occurred over the period of one year or twenty – though the greater sample size helps, it is still the same point in terms of statistical inference, so a long track record does not get you away from this problem).
How does this tie in with saints and witches? People want certainty, and if they can’t get the certainty they want from the empirical, they fall back on superstition and witchcraft, or at least they used to way back when. In some medieval village, a priest prayed and a supplicant was healed. The odds that the supplicant would have healed spontaneously was whatever it was, but there was more of a sense of certainty to feel that it was the manifestation of healing power.
There were false saints and true saints. The difference between them became manifest over time by how frequently the prayers were answered with affirmative results. Not that any saint had to bat a thousand. Sometimes there were understandable, exogenous circumstances that inhibited the saint’s healing talents from being operative, most commonly a lack of righteousness on the part of the supplicant, occasionally an inevitability, a higher power that overshadowed that of the saint. Maybe the will of God, maybe an unknown, evil curse.
I hope the analogy is apparent. And there is a related one, an analogy to Pascal's Wager. The bank should wager that the talent of its star employee exists, because it has much to gain over time if it does, while if it does not exist, the bank will lose little in expected terms. And in a competitive world, it is even worse if they incorrectly let the talent go for lack of proper compensation, because then some competitor will pick it up.
16.9.09
Latest UNITY Journal on Bad Banks

Bad Banks, & how to beat them
September 2009
TABLE OF CONTENTS
5 Bank on a massive campaign
Daphne Lawless, editor of UNITY
11 Why we need to battle the banks
VAUGHAN GUNSON, national chair of Socialist Worker NZ
17 The banks and the Great Implosion
VAUGHAN GUNSON
30 New Zealand’s recession - is the worst over?
ANTHONY Main, Socialist Party (Australia)
34 Are the banks helping?
BILL ROSENBERG, NZ Council of Trade Unions economist
38 A Green response to global market failure
CATHERINE DELAHUNTY and KEVIN HAGUE, Green MPs (New Zealand)
43 International banks exploit the crisis
STEFAN STEINBERG, World Socialist Web Site
47 Are the banks to blame?
Anindya Bhattacharyya and Sadie Robinson, Socialist Worker (Britain)
52 Banks go back to bubble bonuses
ALEX CALLINICOS, Socialist Worker (Britain)
54 The recovery is here! (for Wall Street)
Adam Turl and Alan Maass, Socialist Worker (USA)
60 How the bankers bought Congress
PETRINO DILEO, Socialist Worker (USA)
65 Iceland - what happened?
JACK SMART, Socialist Appeal (Britain)
69 Iceland: devastated by global crisis
Per-Åke Westerlund, Committee for a Workers’ International
72 Can the Left-Greens rescue Iceland?
DEREK WALL, Green Left Network (Britain)
75 Australia: Banks are bastards
PETER ROBSON, Green Left Weekly (Australia)
77 Mexico: Protests target banks
RACHEL EVANS, Green Left Weekly (Australia)
78 Communal banks of Venezuela receive big boost
TAMARA PEARSON, http://www.venezuelanalysis.com/
80 Venezuela will take over private banks that fail
JAMES SUGGETT, http://www.venezuelanalysis.com/
81 Feedback: Letters from Peter de Waal, Bronwen Beechey and Pat O’Dea
To purchase a copy email socialist-worker@pl.net
For details on how to subscribe to UNITY Journal go to New subscription to UNITY Journal
25.8.09
Why we need to battle the banks
by Vaughan Gunson
The recession is taking grip in New Zealand. People are losing their jobs. In some grassroots communities unemployment is already turning into a social crisis.
138,000 people are officially unemployed. Thousands more will be desperately looking for work. And the situation is going to get grimmer as the economy slumps further.
Job losses and income cuts are putting many homeowners in a terrible situation. They can’t meet their mortgage payments. The banks are knocking at the door.
And with property values falling some people are left owing more money to the banks than their home is worth. They face financial ruin.
For grassroots people, this is all very frightening and unfair.
Grassroots mood against the banks
Jobs and homes are gut issues for people. Rising concern about these gut issues is intersecting with a mass mood against the banks.
Last year, RAM activists took a survey out on to the streets, which questioned people about the operations of the banks in this country. Over 90% of people thought the banks were doing no good.
That sentiment has probably hardened. It can be picked up in everyday conversations. It’s reflected in the stories being carried in the media.
You know there’s a mass mood on an issue in New Zealand when two things happen. The first is when it becomes a storyline on Shortland Street. Scotty and Shanti are in trouble with the bank, owing more than their house is worth.
The second indicator of a mass mood is when you start hearing calls for a public enquiry.
This is what the Green, Labour and Progressive parties have been voicing. They want an independent public enquiry into the banks. They’ve sensed the mood and the political opportunities that it presents.
Not right
In the eyes of grassroots people it’s not right that in these times of increasing hardship the banks are continuing their profit run.
The Big Four Australian-owned banks, ANZ National Bank, BNZ, Westpac and ASB, control 90% of the banking industry in New Zealand, putting them in a near-monopoly position.
With so much market control, there’s no pressure to lower interest rates. In 2008, the income the Big Four banks received from loan interest went up a whopping $4.6 million.
As a result the profits of these Aussie-owned banks totalled over $3 billion in 2008, up 3.7% on the year before.
To add fuel to the fire, the Big Four are trying to avoid paying a tax bill of $2.25 billion. BNZ has been convicted by the High Court and told to pay up. Undaunted, the banks are using their extreme wealth to hire teams of lawyers to fight the ruling.
The feelings people have towards the banks has been heading South for sometime. This was before the banks started turfing people out of their homes.
To maintain their own equity position the banks are getting tough and forcing mortgage sales in rapidly increasing numbers. In April this year, there were 250 foreclosures. The numbers are only going to escalate as mortgage pressures worsen with further waves of job losses.
The banks are the bad guys. They could become public enemy number one.
A Bad Banks campaign
In isolation grassroots people have no power against the banks and the laws written to protect the money men. But mass feelings are strong.
It is the job of mass Marxists to tap into those mass feelings. That’s why Socialist Worker is launching a “Bad Banks” campaign.
We believe the Aussie banks are vulnerable to a broad and inclusive campaign that connects with the anger ordinary people feel towards these mega-rich interest gauges.
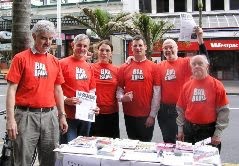
A campaign to expose and shame the banks must be out on the streets. We’ll produce mass leaflets and posters. There will be street stalls. We can build towards publicity pickets outside targeted banks.
We will organise public meetings. Send out media releases, write submissions. We will liaise with others on the left about organising jointly hosted campaign conventions.
The campaign will have a web presence (www.badbanks.co.nz). A Bad Banks Facebook group is up and running (log into Facebook and search for “Bad Banks”).
We will pursue multiple publicity strands that aim to connect with masses of grassroots people.
The first stage of the campaign will be educative. We’ll tell people what the banks are up to. We’ll even explain in popular language “fractional reserve lending”, the credit creation mechanism which literally allows the banks to make money out of thin air.
Our leaflets and other publicity will connect the operations of the banks to the Great Implosion. Explaining what’s happening globally and pointing the finger at who’s responsible. Knowledge, as they say, is the first step to empowerment.
As the Bad Banks campaign evolves we begin to put forward concrete demands and campaign goals. These will emerge through dialogue with other leftists and through listening to grassroots people themselves.
Broad left cooperation
A multi-headed campaign against the banks has the potential to bring networks of indebted homeowners, political parties, unions, community groups and grassroots activists together.
The campaign on the streets should work in tandem with the good initiative of the Green, Labour and Progressive parties to set up their own independent public enquiry into the banks. Parliamentary and street campaigning can both work to build a movement. Linking these two essential political arenas will get the best out of each.
The Bad Banks campaign (or some other campaign name that emerges through discussions with others) could become an invigorating example of broad left political cooperation in practice. This would be extremely positive.
Joint work, sharing of ideas and on-the-ground collective organisation around this “flashpoint” political issue will hopefully encourage a further coming together of broad left forces. Such political cooperation is needed if the left is to rise to the challenge of the biggest economic meltdown since the Great Depression of the 1930s.
Banks and the “bubble economy”
The role the banks and international money men have played in the Great Implosion needs to be widely exposed. The banks are at the centre of the “bubble economy” built on trillions of dollars of debt and speculation.
The floundering of the real economy since the 1970s has seen workers, business and the state increasingly reliant on the extension of credit.
Over the last four decades debt has ballooned. This has allowed the banks and other money lenders, facilitated by governments, to assume a dynamic role within late capitalism.
So entwined are industry giants, big banks and governments, that when the credit crunch hit last year, following the bursting of the worldwide housing bubble, the leaders of the world’s big economies raced to save the banks.
In January this year, Oxfam calculated that $8.424 trillion had so far been raised by governments to bailout the banks and other financial institutions. That’s a vast sum, one which could easily put an end to world poverty.
And the bailouts haven’t stopped. In the US alone, the Obama administration’s bailout commitments could reach as high as $23.7 trillion, according to an official independent report.
However, the bailouts have not prevented the economy from nose-diving, far from it. There’s a global pandemic of job losses and other social miseries. Smaller banks and other financial institutions continue to go under.
Yet some of the big banks, like Goldman Sachs, one of the main players behind the housing bubble, are now posting record profits. With trillions and trillions of government money floating around, these experts at financial manipulation are creaming it.
Helped by government insiders the really big banks are now set on dominating like never before the creation of credit, the fragile base upon which the world economy rests.
The banks left standing are profiting out of lending to cash-strapped governments at high interest rates. They’re speculating again in financial markets. It’s “win-win” for them and “lose-lose” for the rest of us.
Given all the social and environmental problems besetting the world the bailout of bankers is a crime against humanity of obscene proportions.
Debating the nature of capitalism
A system that can divert trillions of dollars to a mega-rich minority and let the majority fend for themselves in an increasingly scary world is an unjust one.
Without a doubt the global economic crisis, and the response by governments, is eroding the legitimacy of the market. And it’s happening in the so called “first world” economies of Northern America and Europe. That’s significant.
A broad campaign against the banks in this country will, if successful, begin to expose the structures of power within monopoly finance capitalism that locks in place gross inequalities globally.
A mass-based campaign against Bad Banks has the potential to stimulate a nationwide debate about the nature of capitalism and the need for a human centred economy. Socialists and leftists from a number of political traditions will want to see this happen.
Lots to learn, lots to get excited about
The Bad Banks campaign that Socialist Worker is initiating will be a long term one. We will be trying things out as we search, hopefully alongside other activists, for a connection with a mass audience.
There’s lots to learn about the operations of the banks in this country and internationally, and how to connect their operations to a system in crisis. It’s going to be a big learning curve for everyone involved.
While the Bad Banks campaign is only just hitting the streets, it’s yet to be fully tested in practice, we do know there’s great resentment towards the banks amongst ordinary Kiwis. We should have confidence that this path will bear fruit for the left in this country. That prospect should be an exciting one.
Vaughan Gunson is the publicity coordinator for the Bad Banks campaign. To contact him with feedback or offers to help, email socialist-worker@pl.net or ph/txt 021-0415 082.
The recession is taking grip in New Zealand. People are losing their jobs. In some grassroots communities unemployment is already turning into a social crisis.
138,000 people are officially unemployed. Thousands more will be desperately looking for work. And the situation is going to get grimmer as the economy slumps further.
Job losses and income cuts are putting many homeowners in a terrible situation. They can’t meet their mortgage payments. The banks are knocking at the door.
And with property values falling some people are left owing more money to the banks than their home is worth. They face financial ruin.
For grassroots people, this is all very frightening and unfair.
Grassroots mood against the banks
Jobs and homes are gut issues for people. Rising concern about these gut issues is intersecting with a mass mood against the banks.
Last year, RAM activists took a survey out on to the streets, which questioned people about the operations of the banks in this country. Over 90% of people thought the banks were doing no good.
That sentiment has probably hardened. It can be picked up in everyday conversations. It’s reflected in the stories being carried in the media.
You know there’s a mass mood on an issue in New Zealand when two things happen. The first is when it becomes a storyline on Shortland Street. Scotty and Shanti are in trouble with the bank, owing more than their house is worth.
The second indicator of a mass mood is when you start hearing calls for a public enquiry.
This is what the Green, Labour and Progressive parties have been voicing. They want an independent public enquiry into the banks. They’ve sensed the mood and the political opportunities that it presents.
Not right
In the eyes of grassroots people it’s not right that in these times of increasing hardship the banks are continuing their profit run.
The Big Four Australian-owned banks, ANZ National Bank, BNZ, Westpac and ASB, control 90% of the banking industry in New Zealand, putting them in a near-monopoly position.
With so much market control, there’s no pressure to lower interest rates. In 2008, the income the Big Four banks received from loan interest went up a whopping $4.6 million.
As a result the profits of these Aussie-owned banks totalled over $3 billion in 2008, up 3.7% on the year before.
To add fuel to the fire, the Big Four are trying to avoid paying a tax bill of $2.25 billion. BNZ has been convicted by the High Court and told to pay up. Undaunted, the banks are using their extreme wealth to hire teams of lawyers to fight the ruling.
The feelings people have towards the banks has been heading South for sometime. This was before the banks started turfing people out of their homes.
To maintain their own equity position the banks are getting tough and forcing mortgage sales in rapidly increasing numbers. In April this year, there were 250 foreclosures. The numbers are only going to escalate as mortgage pressures worsen with further waves of job losses.
The banks are the bad guys. They could become public enemy number one.
A Bad Banks campaign
In isolation grassroots people have no power against the banks and the laws written to protect the money men. But mass feelings are strong.
It is the job of mass Marxists to tap into those mass feelings. That’s why Socialist Worker is launching a “Bad Banks” campaign.
We believe the Aussie banks are vulnerable to a broad and inclusive campaign that connects with the anger ordinary people feel towards these mega-rich interest gauges.
A campaign to expose and shame the banks must be out on the streets. We’ll produce mass leaflets and posters. There will be street stalls. We can build towards publicity pickets outside targeted banks.
We will organise public meetings. Send out media releases, write submissions. We will liaise with others on the left about organising jointly hosted campaign conventions.
The campaign will have a web presence (www.badbanks.co.nz). A Bad Banks Facebook group is up and running (log into Facebook and search for “Bad Banks”).
We will pursue multiple publicity strands that aim to connect with masses of grassroots people.
The first stage of the campaign will be educative. We’ll tell people what the banks are up to. We’ll even explain in popular language “fractional reserve lending”, the credit creation mechanism which literally allows the banks to make money out of thin air.
Our leaflets and other publicity will connect the operations of the banks to the Great Implosion. Explaining what’s happening globally and pointing the finger at who’s responsible. Knowledge, as they say, is the first step to empowerment.
As the Bad Banks campaign evolves we begin to put forward concrete demands and campaign goals. These will emerge through dialogue with other leftists and through listening to grassroots people themselves.
Broad left cooperation
A multi-headed campaign against the banks has the potential to bring networks of indebted homeowners, political parties, unions, community groups and grassroots activists together.
The campaign on the streets should work in tandem with the good initiative of the Green, Labour and Progressive parties to set up their own independent public enquiry into the banks. Parliamentary and street campaigning can both work to build a movement. Linking these two essential political arenas will get the best out of each.
The Bad Banks campaign (or some other campaign name that emerges through discussions with others) could become an invigorating example of broad left political cooperation in practice. This would be extremely positive.
Joint work, sharing of ideas and on-the-ground collective organisation around this “flashpoint” political issue will hopefully encourage a further coming together of broad left forces. Such political cooperation is needed if the left is to rise to the challenge of the biggest economic meltdown since the Great Depression of the 1930s.
Banks and the “bubble economy”
The role the banks and international money men have played in the Great Implosion needs to be widely exposed. The banks are at the centre of the “bubble economy” built on trillions of dollars of debt and speculation.
The floundering of the real economy since the 1970s has seen workers, business and the state increasingly reliant on the extension of credit.
Over the last four decades debt has ballooned. This has allowed the banks and other money lenders, facilitated by governments, to assume a dynamic role within late capitalism.
So entwined are industry giants, big banks and governments, that when the credit crunch hit last year, following the bursting of the worldwide housing bubble, the leaders of the world’s big economies raced to save the banks.
In January this year, Oxfam calculated that $8.424 trillion had so far been raised by governments to bailout the banks and other financial institutions. That’s a vast sum, one which could easily put an end to world poverty.
And the bailouts haven’t stopped. In the US alone, the Obama administration’s bailout commitments could reach as high as $23.7 trillion, according to an official independent report.
However, the bailouts have not prevented the economy from nose-diving, far from it. There’s a global pandemic of job losses and other social miseries. Smaller banks and other financial institutions continue to go under.
Yet some of the big banks, like Goldman Sachs, one of the main players behind the housing bubble, are now posting record profits. With trillions and trillions of government money floating around, these experts at financial manipulation are creaming it.
Helped by government insiders the really big banks are now set on dominating like never before the creation of credit, the fragile base upon which the world economy rests.
The banks left standing are profiting out of lending to cash-strapped governments at high interest rates. They’re speculating again in financial markets. It’s “win-win” for them and “lose-lose” for the rest of us.
Given all the social and environmental problems besetting the world the bailout of bankers is a crime against humanity of obscene proportions.
Debating the nature of capitalism
A system that can divert trillions of dollars to a mega-rich minority and let the majority fend for themselves in an increasingly scary world is an unjust one.
Without a doubt the global economic crisis, and the response by governments, is eroding the legitimacy of the market. And it’s happening in the so called “first world” economies of Northern America and Europe. That’s significant.
A broad campaign against the banks in this country will, if successful, begin to expose the structures of power within monopoly finance capitalism that locks in place gross inequalities globally.
A mass-based campaign against Bad Banks has the potential to stimulate a nationwide debate about the nature of capitalism and the need for a human centred economy. Socialists and leftists from a number of political traditions will want to see this happen.
Lots to learn, lots to get excited about
The Bad Banks campaign that Socialist Worker is initiating will be a long term one. We will be trying things out as we search, hopefully alongside other activists, for a connection with a mass audience.
There’s lots to learn about the operations of the banks in this country and internationally, and how to connect their operations to a system in crisis. It’s going to be a big learning curve for everyone involved.
While the Bad Banks campaign is only just hitting the streets, it’s yet to be fully tested in practice, we do know there’s great resentment towards the banks amongst ordinary Kiwis. We should have confidence that this path will bear fruit for the left in this country. That prospect should be an exciting one.
Vaughan Gunson is the publicity coordinator for the Bad Banks campaign. To contact him with feedback or offers to help, email socialist-worker@pl.net or ph/txt 021-0415 082.
Subscribe to:
Posts (Atom)


 Posts

